“Footfall Rollercoaster: Data Shows High Street Resilience and Risk”
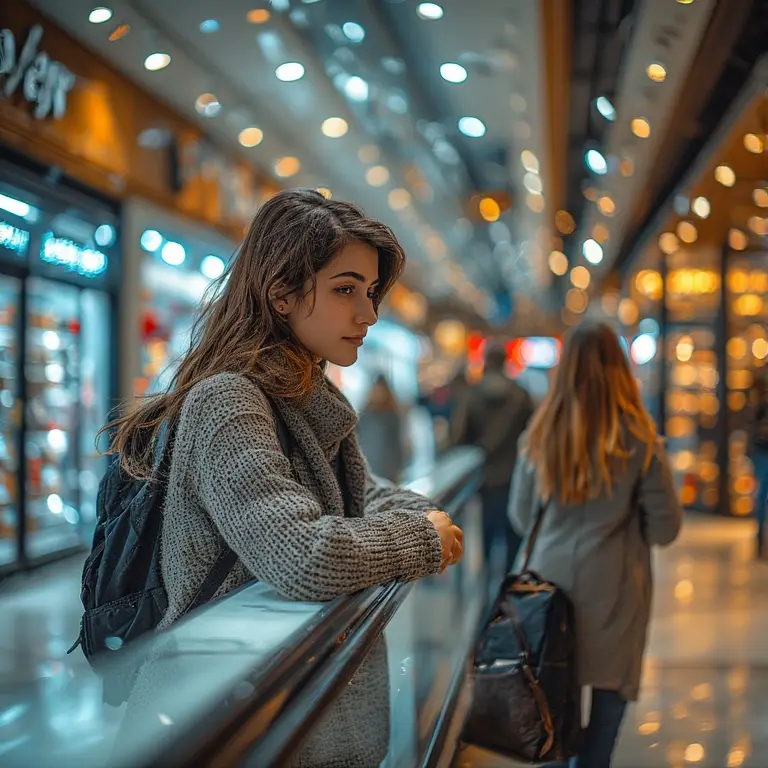
UK high street footfall continues to show a mixed picture — modest growth in some areas tempered by fresh declines elsewhere. While in‑store visits remain common, recent metrics reveal volatility that underscores how fragile physical retail traction remains.
Main Story
Footfall — the lifeblood metric for high streets — has painted a complex picture for UK town centres in 2025, revealing both resilience and fragility as consumer behaviour adapts to economic pressures and changing shopping habits.
In early 2025, foot traffic occasionally posted encouraging trends, with some high streets and retail parks seeing uplift compared to the previous year. In March, overall retail visitor activity surged by mid‑single digits across key retail destinations, partly driven by seasonal events such as Mother’s Day and payday timing. Office workers returning to city centres also supported weekday retail visits, especially in urban areas. FM Business Daily News
However, this momentum proved fleeting in later months. New data reveals that September saw the first annual decline in footfall since 2019, with total retail visits slipping modestly year‑on‑year. High streets bore the brunt of this downturn, underscoring the continued sensitivity of physical retail to broader economic sentiment, weather, and seasonal rhythms. FM Business Daily News
Looking deeper across the year, footfall trends have oscillated. While some months posted gains, others — such as June — experienced significant declines, with UK high street visits falling faster than in shopping centres or retail parks. Analysts highlighted that discretionary spending remains weak, and consumer confidence has not yet stabilised enough to ensure consistent high‑street recovery. BIRA
This volatility matters because consistent footfall underpins dwell time, browsing behaviour, and ultimately in‑store sales. Some retail economists argue that even modest increases in foot traffic can yield disproportionate benefits for local independent retailers, whose margins and survival often hinge on regular visitors.
Despite these ups and downs, one overarching signal persists: physical retail is not dead. Recent research showed that a large majority of Britons still shop in person — with nearly nine in ten visiting bricks‑and‑mortar destinations during key trading months. This suggests that while online shopping remains dominant in headlines, real‑world stores continue to play an important role in daily spending patterns. FashionNetwork
Footfall patterns also differ by geography and retail type. Central city high streets may perform differently from smaller market towns, and retail parks often benefit from free parking and broader destination appeal. Some locations where food, leisure, and mixed‑use offerings have grown are seeing more robust foot traffic — a sign that diversified high‑street ecosystems may be more resilient.
Yet, the broader economic backdrop — including inflationary pressures, cautious consumer sentiment, and competitive online sales — remains a headwind. Retailers and local authorities are watching pivotal trading periods closely, as Christmas and New Year activity will be key to shaping 2026 strategies.
For high streets to stabilise and grow, many observers call for targeted interventions, such as business rate reform, support for independent and experiential retail, and local‑level investment in amenities that enhance the shopper experience. Footfall may be a nuanced metric, but it is arguably the truest barometer of present‑day high‑street health — and right now it tells a story of uneven recovery and ongoing challenge.